One trust standard for the entire mortgage chain
That is Goed IDee, HDN's market standard for digital identification and signing for a mortgage. The home buyer establishes their identity with us once, and every party in the chain builds on it.
From again and again to just once
For a mortgage, the adviser wants to see a copy of the identity document, and the lender then asks for it once more. The offer often still goes out on paper to be signed. All that checking and asking again takes time. With Goed IDee, the home buyer identifies once digitally and the rest of the chain works with that one identification, up to and including the signature. And because copies no longer circulate, the risk of identity fraud is smaller.
Without Goed IDee
Copy of identity document


Adviser
Provide another copy
Lender
Sign on paper

Signing
With Goed IDee

Identify digitally once
Reuse the same identification
Sign digitally, qualified


Adviser
Lender

Signing
Our role in Goed IDee
We are a qualified trust service provider (QTSP), licensed by the Dutch Authority for Digital Infrastructure (RDI). Within Goed IDee we take care of the identification, the consent and the signature. Because it is a shared standard, the whole chain can then work with it.
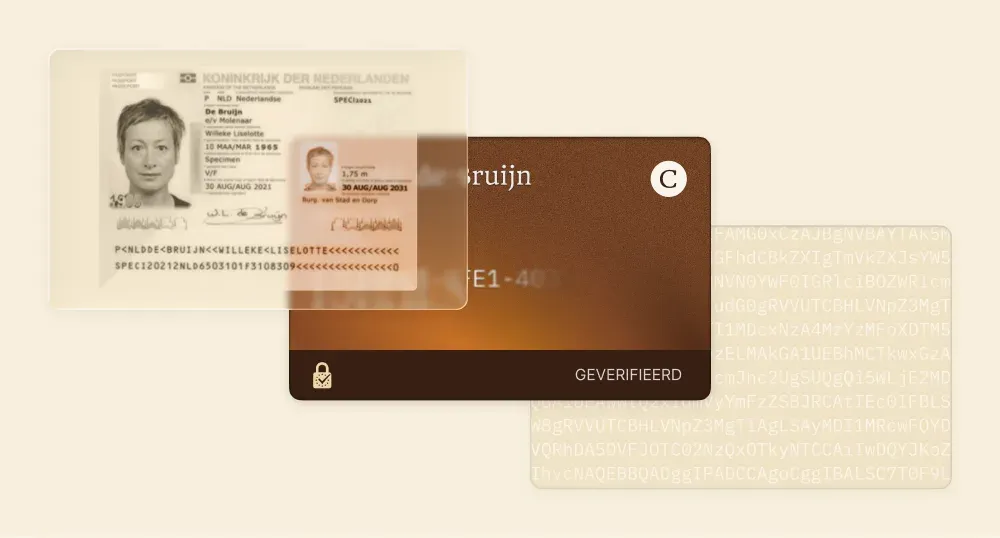
Establishing identity
The home buyer identifies at eIDAS assurance level high, without a copy of the identity document. This lets the adviser and the lender meet their Wwft customer due diligence without physical verification.
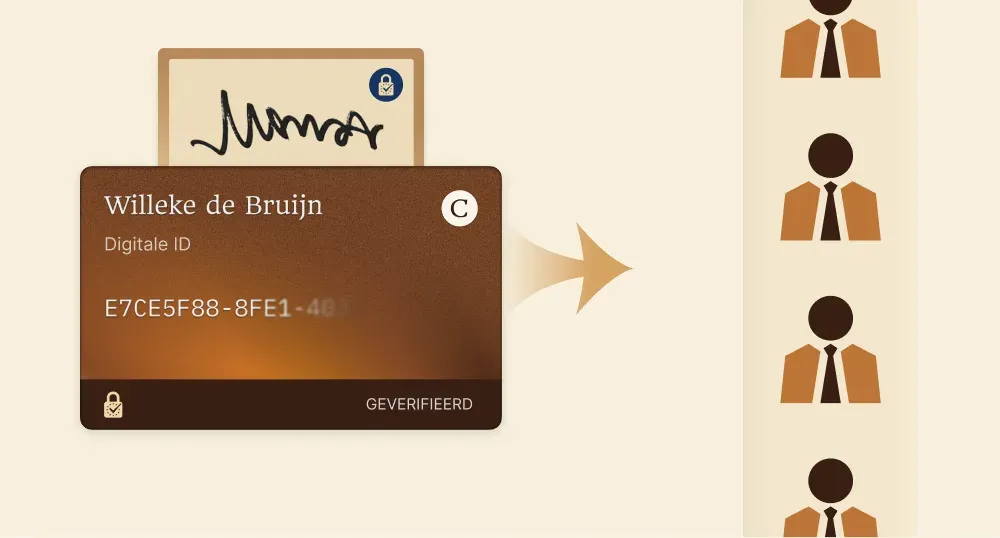
Recording consent
The customer gives consent to share their identity and data with the parties working on their mortgage, for a specific purpose. That consent travels with the file.
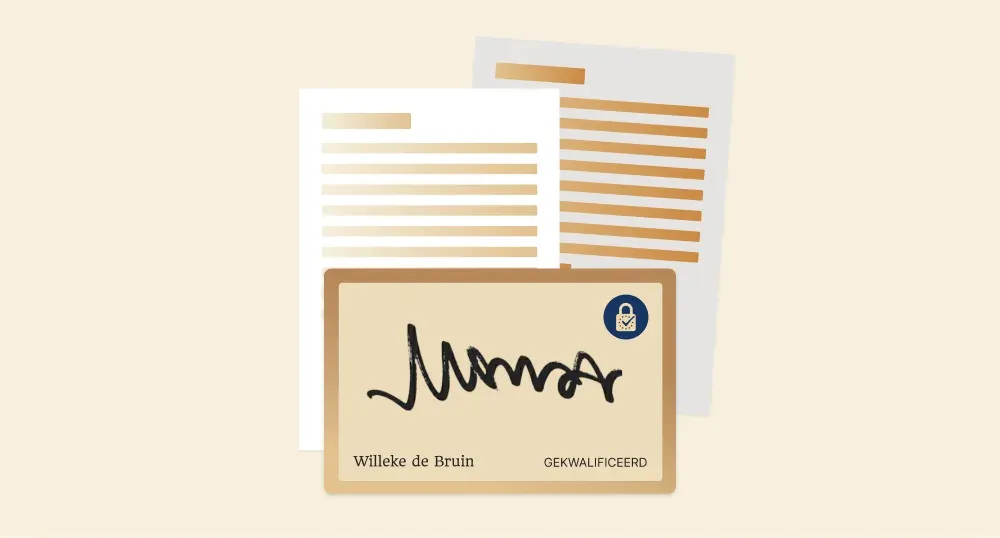
Qualified signing
The home buyer signs the binding offer digitally, legally equivalent to a signature on paper and linked to the identity we established earlier.

Want to know how trust services can be implemented in your organisation?
Leave your details and our team will get in touch with you.
How a mortgage works with Goed IDee
Arranging a mortgage takes weeks, with an adviser, a lender, an appraiser and a civil-law notary who all need something from the buyer. Below you can see how we improve that together.
"With this new market standard, we can speed up the mortgage process by as much as five days."
- 1
Purchase agreement
Buyer and seller sign, usually with a financing condition. From that moment the statutory three-day cooling-off period runs and the buyer starts looking for a mortgage.

Many estate agents already identify the buyer through us at this point. That identification is reused further along the chain.
- 2
Advice, identification and consent
The adviser maps out the financial picture. The customer identifies digitally and gives consent for the use of their data in the rest of the process.
We establish the identity at eIDAS assurance level high and record the consent.
- 3
Data from the source
Income, pension and debts come straight from bodies such as UWV and the Dutch Tax Administration, retrieved by a source data provider such as our partner Ockto. That is possible because the customer gave consent for it in step 2. They no longer have to scan or upload anything themselves.
Together with Ockto, we bring this data and the identification from step 2 together in one process.
- 4
Application and assessment
The complete file goes to the lender through the HDN network. The lender assesses the application, together with the valuation of the home. Customer and adviser can see how things stand along the way.
The lender builds on our identification, so identity documents no longer travel with the file.
- 5
Offer and digital signing
The customer receives the mortgage offer, the lender's binding offer, and signs it with a qualified electronic signature.
We safeguard the signature and the identity of the signer.
- 6
Civil-law notary and Land Registry
The civil-law notary draws up the deed of transfer and the mortgage deed, the customer signs them and the Land Registry registers the mortgage. With that, the mortgage is complete.
The chain does not close here yet. We are working to make sure the customer does not have to identify again at the civil-law notary either.
Source data, identity and signature in one process
The revised eIDAS Regulation sets new requirements for digital identification, and iDIN is being phased out. That is why we have been working with Ockto since September 2026: they provide the reliable source data, we provide the trust on top of it. Together we bring Goed IDee to the whole housing sector faster.
Would you like to talk about this further?
Leave your details and our team will get in touch with you.